New Construction vs Existing Homes: How to Choose What Fits You Best

Nicole Mickle
Realtor, Olympus Executive Realty
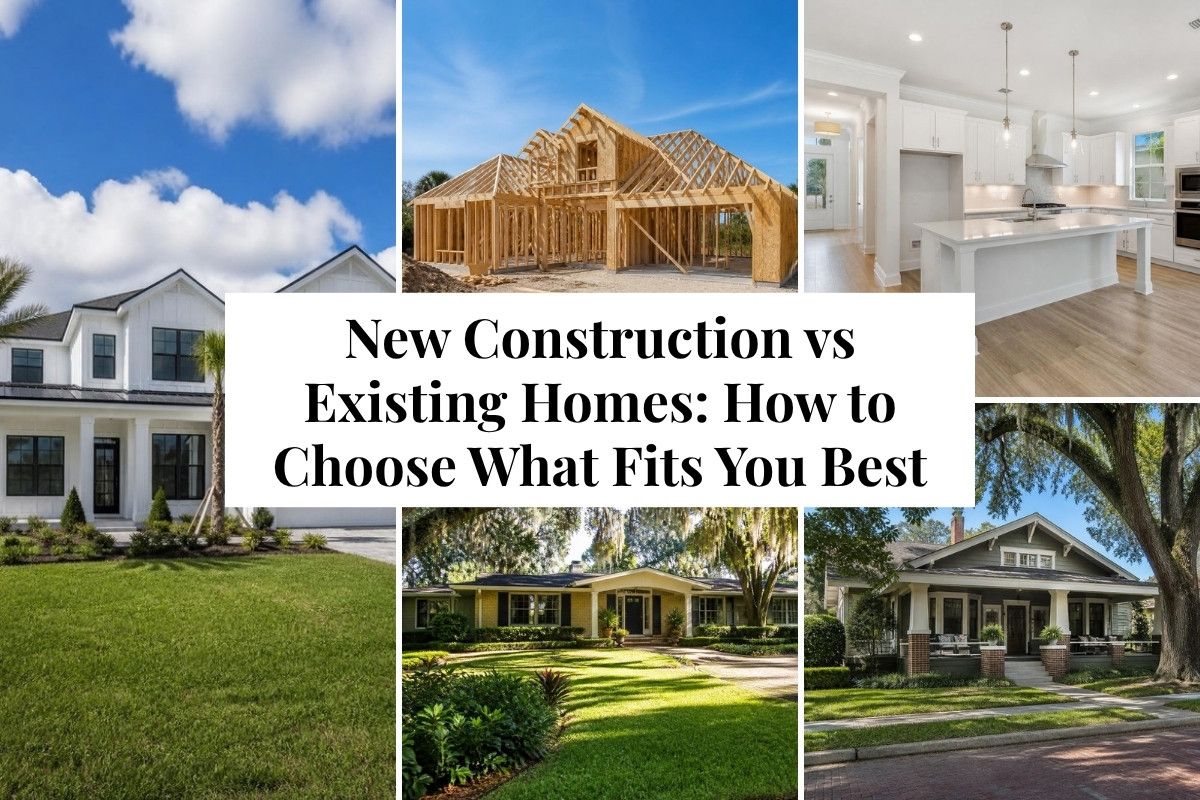
Buying a home often comes with one major decision: should you choose new construction or an existing home? Each option has different implications for your price, timeline, customization choices, maintenance costs, and preferred Orlando-area location.
This guide breaks down the real differences between new construction and existing homes. You will learn what to expect with builder contracts and warranties and how inspections and appraisals work. You'll also see what energy efficiency labels actually mean and when an older home’s age matters for safety and maintenance.
Whether you want a just‑finished place with everything under warranty or a character home in a mature neighborhood, use this to make a confident choice. Are you comparing Orlando-area builders with resale homes? I can identify suitable communities, compare builder incentives and upgrade costs, and evaluate how each option fits your budget, commute, and timeline.
TL;DR
- New construction may require a longer or less predictable timeline, but it can provide more customization, newer energy-saving features, and builder warranty coverage.
- Existing homes often provide faster move-in timelines and more established locations, but their age and condition may lead to earlier repairs or replacements.
- Always plan for inspections and appraisals. Rules like the 3‑day Closing Disclosure timeline apply to both.
- For most homes built before 1978, federal law requires sellers to disclose known lead-based paint information and provide required lead documents before the buyer becomes obligated to purchase.
What New Construction Really Means
New construction typically falls into three buckets:
- To-be-built: You select a lot, floor plan, and available options before construction begins, subject to the builder’s contract, permitting, and schedule.
- Spec or inventory home: The builder has started or finished the home, although you may still pick some finishes.
- Custom: You hire an architect and builder and typically have greater control over the home’s design, materials, and layout.
Production builders commonly use their own purchase agreements rather than the standard contracts often used for resale homes. These agreements may address deposits, upgrade selections, change orders, construction delays, inspections, financing, and cancellation rights.
For an FHA-insured new construction purchase, the builder and buyer generally execute HUD’s Warranty of Completion. It provides one year to report covered construction defects or substantial nonconformity with approved plans, beginning at title transfer or initial occupancy, whichever occurs first.
Before signing, you should understand the deposit rules, financing deadlines, inspection access, upgrade terms, and cancellation provisions. I track these transaction details and compare the builder’s offer with other available communities.
What Existing Homes Offer
Existing homes often close faster than properties that still need to be built, although a completed builder inventory home may offer a similar timeline. You can see the exact house, yard, street, and noise at different times of day.
The tradeoff is that major components such as the roof, HVAC system, plumbing, electrical system, and water heater may have fewer useful years remaining. For older homes, building practices and energy performance often lag newer standards, though many owners have upgraded over time.
For most homes built before 1978, federal law requires the seller to disclose known lead-based paint information, provide available reports, and give the buyer the required federal lead warning materials. This is a safety issue for families planning renovations that disturb painted surfaces.
Cost, Timeline, and Risk
Your total costs and timeline depend on whether you choose a new construction home or an existing property. Understanding where unexpected expenses and delays can occur helps you plan more confidently.
For new construction:
- Base prices may exclude lot premiums, upgrades, HOA fees, closing costs, and other community-related expenses.
- Extensive upgrades can affect the appraisal if nearby comparable homes don't support the final contract price.
- Construction timelines depend on permitting, labor, weather, materials, utilities, and required inspections.
- Completion dates can change, so avoid locking in moving, lease, or travel plans too early.
For existing homes:
- The asking price is only part of your total cost. Inspections, insurance, appraisals, and repairs can affect your budget.
- Depending on your contract, inspection results may allow you to request repairs, negotiate credits, or cancel during the inspection period.
- Most existing homes can close once financing, title, appraisal, insurance, and other transaction requirements are complete.
- For most mortgage loans, your lender must provide the Closing Disclosure at least three business days before closing.
As your realtor, let me help you compare builder pricing, estimate ownership costs, and track important transaction deadlines, especially if you're relocating to the Orlando area.
To compare monthly payments side by side, including property taxes, insurance, and HOA or CDD fees, run both scenarios through my Orlando mortgage calculator.
Quality, Efficiency, and Warranties
Construction quality, energy performance, and warranty coverage can vary between homes. Knowing what inspections, certifications, and warranties do, and do not, cover helps you make a more informed purchase.
For inspections:
- Municipal inspections verify building code compliance but don't replace an independent home inspection.
- If your builder allows it, consider a pre-drywall inspection, a final inspection, or both.
- Home inspectors follow established Standards of Practice for evaluating a home's visible components.
For energy efficiency:
- New homes often meet newer building and energy standards, but efficiency varies by builder and construction quality.
- Some homes earn independent ENERGY STAR certification after completing required testing and verification.
- Ask whether the home is ENERGY STAR certified or built to current Florida energy code standards.
- Request supporting documents, such as energy ratings, certificates, or testing results for advertised efficiency claims.
For warranties:
- Builder warranties vary in length, coverage, exclusions, and claim procedures depending on the builder.
- FHA-insured new construction includes HUD's one-year Warranty of Completion, with many builders also offering additional structural coverage.
- Home service contracts for existing homes are optional and aren't the same as homeowners insurance.
- Review covered systems, exclusions, claim procedures, service fees, and coverage limits before purchasing a home service contract.
Location, Lifestyle, and Future Value
New communities may offer recently built amenities and coordinated home designs, but lot sizes, street layouts, fees, and construction activity vary by development. You may wait for trees to mature and for nearby retail to arrive.
Existing Orlando neighborhoods may offer mature landscaping, established services, more architectural variety, and a clearer picture of traffic and commute patterns.
Future value hinges on local supply and demand, school and job trends, and the home’s condition and efficiency upgrades. Neither option wins on appreciation every time. Choose the lifestyle fit first, then buy the best home you can in that category.
New Build vs Existing: Quick Comparison
Side-by-side breakdowns highlight key differences in customization, timelines, and long-term expenses so you feel confident choosing between a brand-new space and a pre-loved residence.
| Factor | New construction | Existing home |
|---|---|---|
| Customization | High during design; limited on spec homes | Low to medium via renovations after closing |
| Timeline to move | Variable for to-be-built homes; potentially shorter for completed inventory | Often shorter, subject to financing, inspections, title, and the seller’s timeline |
| Energy efficiency | Often higher; ENERGY STAR or similar possible | Varies by age and upgrades |
| Repairs near term | Generally fewer age-related repairs, but defects may still occur; coverage depends on the warranty | Condition varies; use the inspection and system ages to estimate near-term costs |
| Appraisal risk | Can rise with heavy upgrades | Centered on condition and comps |
| Inspection strategy | Pre-drywall and final private inspections advised | Standard private inspection advised |
| Closing process | Builder contract; same mortgage disclosures apply | Standard purchase contract; same disclosures apply |
| Price transparency | Base price plus options and lot premiums | Asking price with visible condition |
| Neighborhood maturity | Developing amenities | Established services and landscaping |
| Community costs | May include lot premiums, HOA dues, amenity fees, or CDD assessments | May include HOA dues, maintenance needs, or special assessments |
How Inspections and Appraisals Protect You
An appraisal is an independent opinion of value commonly ordered by the lender to evaluate the property securing the loan. If the appraisal is lower than the contract price, your options depend on the purchase contract and loan terms. I can review the transaction choices and negotiate when appropriate, while your lender explains the financing requirements.
Separately, an independent home inspector evaluates visible systems and components and provides a report that can help you plan repairs and make transaction decisions. For new construction, consider phased inspections so defects are corrected before finishes hide them.
Examples
These scenarios show how common issues may arise when comparing new construction with an existing home.
A To‑Be‑Built Townhome
A buyer selects a to‑be‑built end unit, adds a bedroom and mid‑grade finishes, and the price climbs. The lender orders an appraisal based on plans and specs.
The appraiser supports value, but the private pre‑drywall inspection finds missing fire blocking and an HVAC duct crimp. The builder fixes both under the contract. At closing, the buyer receives HUD’s one‑year builder warranty with instructions on how to submit claims.
A 1968 Ranch in a Mature Suburb
A buyer loves the street and yard. The agent flags the pre‑1978 build date, so the seller provides the federally required lead‑paint disclosure and past test results. The inspection shows an aging furnace and GFCI updates needed in the kitchen.
The buyer negotiates a credit for the furnace and closes on time after receiving the Closing Disclosure three business days before signing. In year one, the buyer tackles insulation and air sealing to reduce utility bills.
Actionable Steps / Checklist
Use this checklist to compare your options and track important questions before signing a contract or moving toward closing.
- Set a ceiling price that includes options or post‑closing repairs, not just base price or list price.
- Request the current price sheet, lot premium, included features, upgrade pricing, incentive terms, estimated property taxes, HOA dues, and any CDD assessments.
- For new construction, confirm your contractual inspection rights and schedule permitted inspection stages. For an existing home, use the inspection findings and specialist evaluations to estimate upcoming expenses.
- Request the ENERGY STAR certificate or blower‑door test results if advertised.
- Confirm warranty terms in writing, including who administers it, claim steps, timelines, and what is excluded or capped.
- Plan for the appraisal to avoid over‑customizing beyond neighborhood norms.
- Track closing milestones. Watch for the lender’s Closing Disclosure and review it carefully at least three business days before closing.
- If buying pre‑1978, follow lead‑safe practices for any renovation and keep all disclosures and test records.
Glossary
Straightforward term definitions remove confusion around appraisals, disclosures, and builder standards.
- Appraisal: An independent opinion of a home’s market value, commonly ordered by the lender as part of the mortgage process.
- Closing Disclosure: A five‑page form with your final loan terms and costs; by rule, you get it at least three business days before closing.
- Builder Warranty: The limited warranty a builder provides on new construction; FHA‑insured loans require a one‑year HUD Warranty of Completion.
- Home Warranty: A service contract that may cover certain home systems or appliances; it's not homeowners insurance.
- Pre‑Drywall Inspection: A private inspection before walls are closed, focused on framing, wiring, plumbing, and HVAC rough‑ins.
- Spec Home: A builder‑owned home started without a buyer; finishes may be preselected, but delivery is usually faster.
- ENERGY STAR Certified New Home: A home that meets EPA program requirements for energy efficiency, verified by testing and inspection.
- Lead‑Based Paint Disclosure: A federal requirement for most housing built before 1978 to inform buyers of known lead hazards.
Final Thoughts
There's no universal winner between new construction and an existing home. The better choice depends on your budget, timeline, preferred Orlando-area location, tolerance for repairs, and interest in selecting finishes.
I guide buyers in comparing active builders with established neighborhoods, gather the costs and fees associated with each option, and manage the real estate transaction from the initial search through closing. This support is also available to relocating buyers who need virtual tours and remote coordination.
Start by identifying the Orlando neighborhoods and new-build communities that fit your commute, budget, and lifestyle. I can prepare a focused comparison of relevant Orlando-area homes and builder communities based on the priorities you provide. You remain in control of the final property, financing, inspection, and purchase decisions.
Frequently Asked
Questions, answered
Do I still need an inspection on a new build?
Yes. Municipal code inspections aren't a substitute for a private inspector working solely for you. Phased inspections can catch issues before finishes hide them.
What happens if my new home doesn't appraise at the contract price?
Your options depend on the builder contract and financing terms. You may be able to challenge the appraisal, revise eligible selections, renegotiate, change financing, or pay part of the difference in cash.
Are new homes always cheaper to run?
New homes are often cheaper in the long run, but not always. ENERGY STAR certified homes and tighter codes can lower utility costs. Ask for documentation and test results to be sure.
How long does a builder warranty last?
Warranty terms vary by builder and coverage type. For FHA-insured new construction, HUD’s Warranty of Completion generally provides a one-year reporting period for covered defects or substantial nonconformity, beginning at title transfer or initial occupancy, whichever occurs first.
What should I watch for on closing week?
Review your Closing Disclosure with your lender, verify the required cash and loan terms, and confirm that agreed repairs or builder items are documented before closing. Part of my work is to track contractual items and coordinate the final walkthrough.